The #1 Problem We See With New Bakery Owners
From years of hands-on bakery equipment experience, And the number one problem I see isn't finding customers or baking great bread—it's figuring out how to pay for the equipment.
I've seen too many talented bakers with great recipes and solid business plans get stuck because they couldn't come up with $30,000-$50,000 upfront for a divider, mixer, and oven. Some end up buying cheap equipment that breaks down in 6 months. Others delay their opening by a year or more trying to save enough cash.
The good news? You don't need to pay cash. There are multiple financing and leasing options available for commercial bakery equipment—and we've helped customers from Nigeria to Vietnam get approved even with less-than-perfect credit.
"I had my eye on a full automatic divider rounder for 2 years but couldn't afford the $18,000 price tag. With equipment financing, I put $1,800 down and pay $350 a month. The machine pays for itself—I went from 500 pieces a day to 3,000. Best decision I ever made."
— Ahmed K., Jeddah, Saudi Arabia • Complete Bakery Line Owner
In This Guide
6 Financing Options for Bakery Equipment
Not all financing is created equal. Here are the six most common options we see our customers use, ranked from most to least popular:
1. Equipment Financing Loan (Most Popular)
This is the most common option for our customers. An equipment financing loan is specifically designed for purchasing machinery. The equipment itself is collateral, so you don't need to put up your home or other assets.
- Down payment: 10-20% (some lenders offer 0% down for well-qualified buyers)
- Interest rates: 6-20% depending on credit
- Terms: 3-7 years
- Best for: Established businesses and startups with good credit
2. Equipment Lease (Second Most Popular)
With a lease, you're importantly renting the equipment for a set period. At the end of the lease term, you typically have the option to buy the equipment for its fair market value (usually 10-20% of the original price), return it, or upgrade to newer equipment.
- Down payment: Usually 0-2 months' payments
- Monthly payments: 20-30% lower than loan payments
- Terms: 2-5 years
- Best for: Businesses that want to upgrade equipment regularly or have limited upfront cash
3. SBA Loan (US Customers Only)
If you're in the United States, SBA (Small Business Administration) loans offer Some best rates and terms available. The SBA guarantees a portion of the loan, which reduces the lender's risk and allows for lower interest rates and longer repayment terms.
- Interest rates: 5-10%
- Terms: Up to 10 years for equipment
- Down payment: 10-20%
- Best for: US-based businesses with good credit and a solid business plan
4. Business Line of Credit
A business line of credit gives you access to a pool of money that You can draw from as needed. You only pay interest on the amount you actually borrow. This is flexible but usually has higher interest rates than equipment-specific loans.
- Interest rates: 8-25%
- Best for: Businesses with ongoing equipment needs or those that want flexibility
5. Personal Loan or Credit Cards
Some startup owners use personal loans or credit cards to finance their first equipment. This can work for smaller purchases ($5,000-$10,000), but we generally don't recommend it for larger equipment purchases because interest rates are high and it puts your personal credit at risk.
- Interest rates: 15-30% for credit cards, 10-20% for personal loans
- Best for: Small equipment purchases or when You can't qualify for business financing
6. Seller Financing (Sometimes Available)
In some cases, equipment suppliers (including us) may offer direct financing or work with preferred lenders to make the process smoother. We don't currently offer direct financing, but we can provide the detailed invoices and equipment specifications that lenders need to process your application quickly.
Financing Options Comparison Table
*Lease payments include a built-in financing cost, but no separate interest rate is quoted.
Leasing vs Buying: Which Is Right for You?
This is the question we get asked most often. Here's a simple structure to help you decide:
Choose to BUY If:
- ✓ You plan to keep the equipment 5+ years
- ✓ You want to build equity in the equipment
- ✓ You can claim depreciation on taxes
- ✓ You've the down payment (10-20%)
- ✓ The equipment is core to your business (divider, mixer, oven)
- ✓ You don't need the latest technology every 2-3 years
Choose to LEASE If:
- ✓ You want lower monthly payments
- ✓ You've limited upfront cash
- ✓ You plan to upgrade every 2-3 years
- ✓ The technology changes quickly (POS, automation)
- ✓ You want to preserve your credit line for other needs
- ✓ You're testing a new product line and aren't sure of long-term needs
Our recommendation for most bakery owners: Buy your core equipment (dough divider, spiral mixer, rotary oven) because these machines last 10-15 years and are the heart of your production. Lease technology that changes quickly (POS systems, software, some automation).
We've seen customers save thousands by buying our automatic divider rounders and rotary ovens with financing rather than leasing—the monthly payment is only slightly higher, and after 5 years they own the equipment outright.
Credit Score Requirements and How to Get Approved
Your credit score is the single biggest reason in determining whether you get approved and what interest rate you'll pay. Here's what lenders typically look for:
Credit Score Tiers
What to Do If Your Credit Is Below 650
Don't despair—we've helped many customers with credit scores in the 550-650 range get approved. Here are strategies that work:
- Apply with a co-signer who has good credit (700+). This by a lot improves your approval odds and can lower your interest rate by 5-10%.
- Make a larger down payment (25-30%). Lenders see this as reduced risk and are more likely to approve you.
- Start with smaller equipment ($5,000-$10,000), make payments on time for 6-12 months, then refinance or add more equipment.
- Provide a solid business plan with realistic financial projections showing how the equipment will generate revenue.
- Show consistent business revenue—even if your personal credit is weak, 6+ months of consistent bank deposits can help.
- Work with lenders that specialize in bad credit—some online lenders focus on borrowers with lower credit scores (though rates will be higher).
Real Costs: Interest Rates, Fees, and Monthly Payments
Let's look at real numbers. Here's what a $50,000 bakery equipment package (divider + mixer + oven) actually costs with different credit profiles:
*From 5-year (60 month) loan term. Monthly payments calculated using standard amortization formula.
Important Insight: The True Cost of Waiting
Many owners wait 6-12 months to save cash and avoid interest. But if an automatic divider increases your production from 500 to 3,000 pieces a day, that's $500-$1,500 in additional daily revenue. Even at 20% interest, the equipment pays for itself in 2-3 months. Don't let perfect credit stop you from growing your business.
Step-by-Step Application Process
Here's exactly what to expect when applying for equipment financing:
Get Your Equipment Quote
Contact us for a detailed quote including equipment specifications, pricing, and delivery terms. Lenders need this to process your application. We typically provide quotes within 24 hours.
Gather Your Documents
Prepare: 2-3 years tax returns, 3-6 months bank statements, business plan, personal financial statement, driver's license, EIN. Having these ready speeds up approval by 1-2 weeks.
Apply with 2-3 Lenders
Don't apply with just one lender. Different lenders have different credit requirements and rates. Applying with 2-3 lenders lets you compare offers and choose the best terms. Multiple applications within a 14-day window count as a single inquiry on your credit report.
look over and Compare Offers
Look at the total cost (interest + fees), not just the monthly payment. Check for prepayment penalties, late fees, and balloon payments. Ask each lender for a complete amortization schedule.
Sign Documents and Pay Down Payment
Once you choose a lender, sign the loan agreement and pay your down payment. Most lenders can fund within 3-7 business days after approval.
Lender Pays Us, Equipment Ships to You
The lender pays us directly, and we ship your equipment. You start making monthly payments to the lender. We provide installation support and training to help you get up and running quickly.
5 Common Mistakes to Avoid
We've seen customers make these mistakes over and over. Avoid them and you'll save thousands:
Mistake #1: Only Looking at the Monthly Payment
A lower monthly payment might mean a longer term, which means more total interest. Always calculate the total cost (principal + interest + fees) over the life of the loan. A $950/month payment for 5 years ($57,000 total) is better than $800/month for 7 years ($67,200 total).
Mistake #2: Not Reading the Fine Print
Watch for prepayment penalties (some lenders charge 2-5% if you pay off early), balloon payments (a large lump sum due at the end), and variable interest rates (which can increase over time). Ask the lender to point out all fees in writing before signing.
Mistake #3: Applying with Too Many Lenders
While applying with 2-3 lenders is smart, applying with 10+ can hurt your credit score. Each application typically causes a hard inquiry on your credit report, which can lower your score by 2-5 points. Keep applications within a 14-day window to minimize the impact.
Mistake #4: Overborrowing
Just because you're approved for $100,000 doesn't mean You should borrow $100,000. Borrow only what you need for the equipment that will generate immediate revenue. Start with core equipment (divider, mixer, oven) and add more as your business grows and cash flow improves.
Mistake #5: Not Planning for Additional Costs
The equipment price isn't the total cost. Budget an additional 10-15% for shipping, installation, electrical work, training, and initial supplies. Many owners are surprised when a $50,000 equipment package ends up costing $57,000 all-in. Reason these costs into your loan amount.
Popular Equipment Our Customers Finance
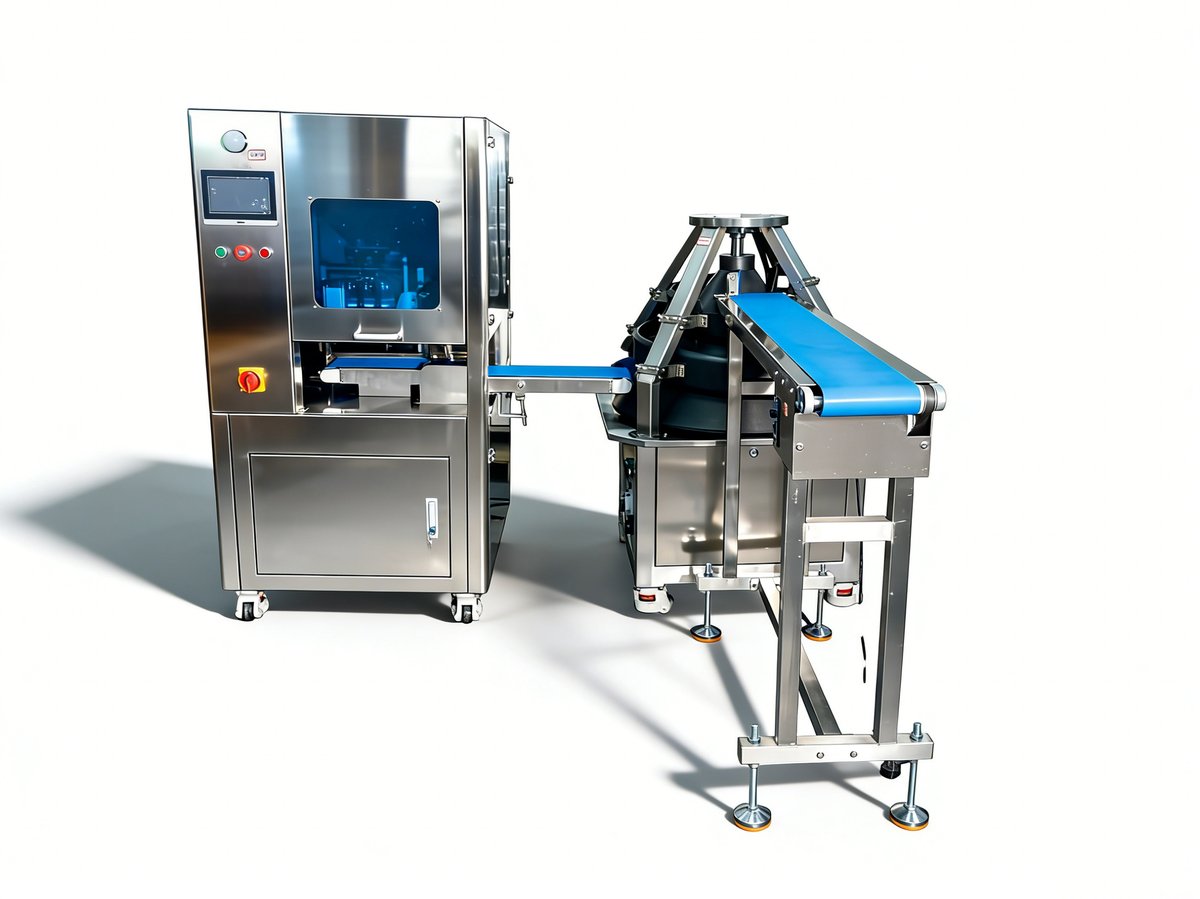
These are the machines our customers most often finance. Click any product to see detailed specifications and get a quote:
📋 Bakery Equipment Checklist
Download our complete bakery equipment checklist with budget estimates for 5 different bakery types.
Free Bakery Equipment Checklist →📋 Bakery Equipment ROI Calculator
Use our interactive ROI calculator to see how quickly your bakery equipment investment pays off.
Calculate Your Equipment ROI →📋 Bakery Equipment Maintenance Calendar
Get our printable maintenance calendar to keep your bakery equipment running at peak performance.
Printable Maintenance Calendar →📋 Bakery Equipment Energy Cost Calculator
Estimate your bakery equipment energy costs and find ways to reduce your utility bills.
Calculate Energy Costs →🏭 Bakery Equipment Capacity Calculator
Not sure what size equipment you need? Use our free interactive calculator to find the perfect dough divider, mixer, oven, and proofer capacity for your production volume.
Calculate Your Equipment Needs →⚖️ Bakery Equipment Comparison Tool
Compare dough dividers, spiral mixers, ovens, proofers and dough sheeters side by side. View specs, prices, capacity and features to find the best equipment for your bakery.
Compare Equipment Now →Often Asked Questions
Here are the questions we get asked most often about bakery equipment financing:
Q: What credit score do I need to finance bakery equipment?
A: Most equipment financing lenders require a minimum credit score of 600-650. However, we've helped customers with scores as low as 550 get approved by providing a solid business plan and showing consistent revenue. If your credit is below 600, consider a co-signer, a larger down payment (20-30%), or starting with smaller equipment and upgrading as your business grows.
Q: Is it better to lease or buy bakery equipment?
A: It depends on your situation. Leasing is better if you need the latest technology, want lower monthly payments, or plan to upgrade every 3-5 years. Buying is better if you plan to keep the equipment for 5+ years, want to build equity, or can claim depreciation on your taxes. For our customers, we typically recommend buying for core equipment (dividers, mixers, ovens) and leasing for technology that changes quickly (POS systems, automation). Most of our customers end up buying because commercial bakery equipment lasts 10-15 years with proper maintenance.
Q: How much does a typical bakery equipment financing loan cost?
A: A typical $50,000 equipment financing loan for a bakery with good credit (700+) has an interest rate of 6-12% and a monthly payment of $950-$1,150 over 5 years. For fair credit (600-700), rates are 12-20% with monthly payments of $1,100-$1,400. Total interest paid over 5 years ranges from $8,000 to $25,000 depending on your credit score. We always recommend getting quotes from 2-3 lenders and comparing the total cost, not just the monthly payment.
Q: Can I get financing for used bakery equipment?
A: Yes, many lenders offer financing for used commercial bakery equipment, but the terms are usually less favorable. Used equipment loans typically require a 15-25% down payment (vs 10% for new), have higher interest rates (2-5% more), and shorter repayment terms (3-4 years vs 5-7 years). The equipment must also be appraised and meet the lender's age requirements (usually under 10 years old). We've seen customers save 30-50% by buying used, but the financing savings are often offset by higher maintenance costs and shorter equipment lifespan.
Q: What documents do I need to apply for bakery equipment financing?
A: Most lenders require: 1) A completed application with personal and business information, 2) 2-3 years of business tax returns (or personal returns if startup), 3) 3-6 months of business bank statements, 4) A business plan or financial projections, 5) A quote or invoice for the equipment you're financing, 6) Personal financial statement, 7) Your driver's license and EIN. If you're a startup (less than 2 years in business), You can also need a personal guarantee and a larger down payment. We recommend having all documents ready before applying to speed up the approval process.
Ready to Get the Equipment You Need?
Contact us today for a detailed equipment quote. We'll provide the specifications and pricing You should apply for financing—and support you through the entire process.
Email: sales@yuanmhe.com | WhatsApp: +86 137 5500 7928